

When other persons use the information materials on the corporate website, links to the company's corporate website must be provided!
When other persons use the information materials on the corporate website, links to the company's corporate website must be provided!
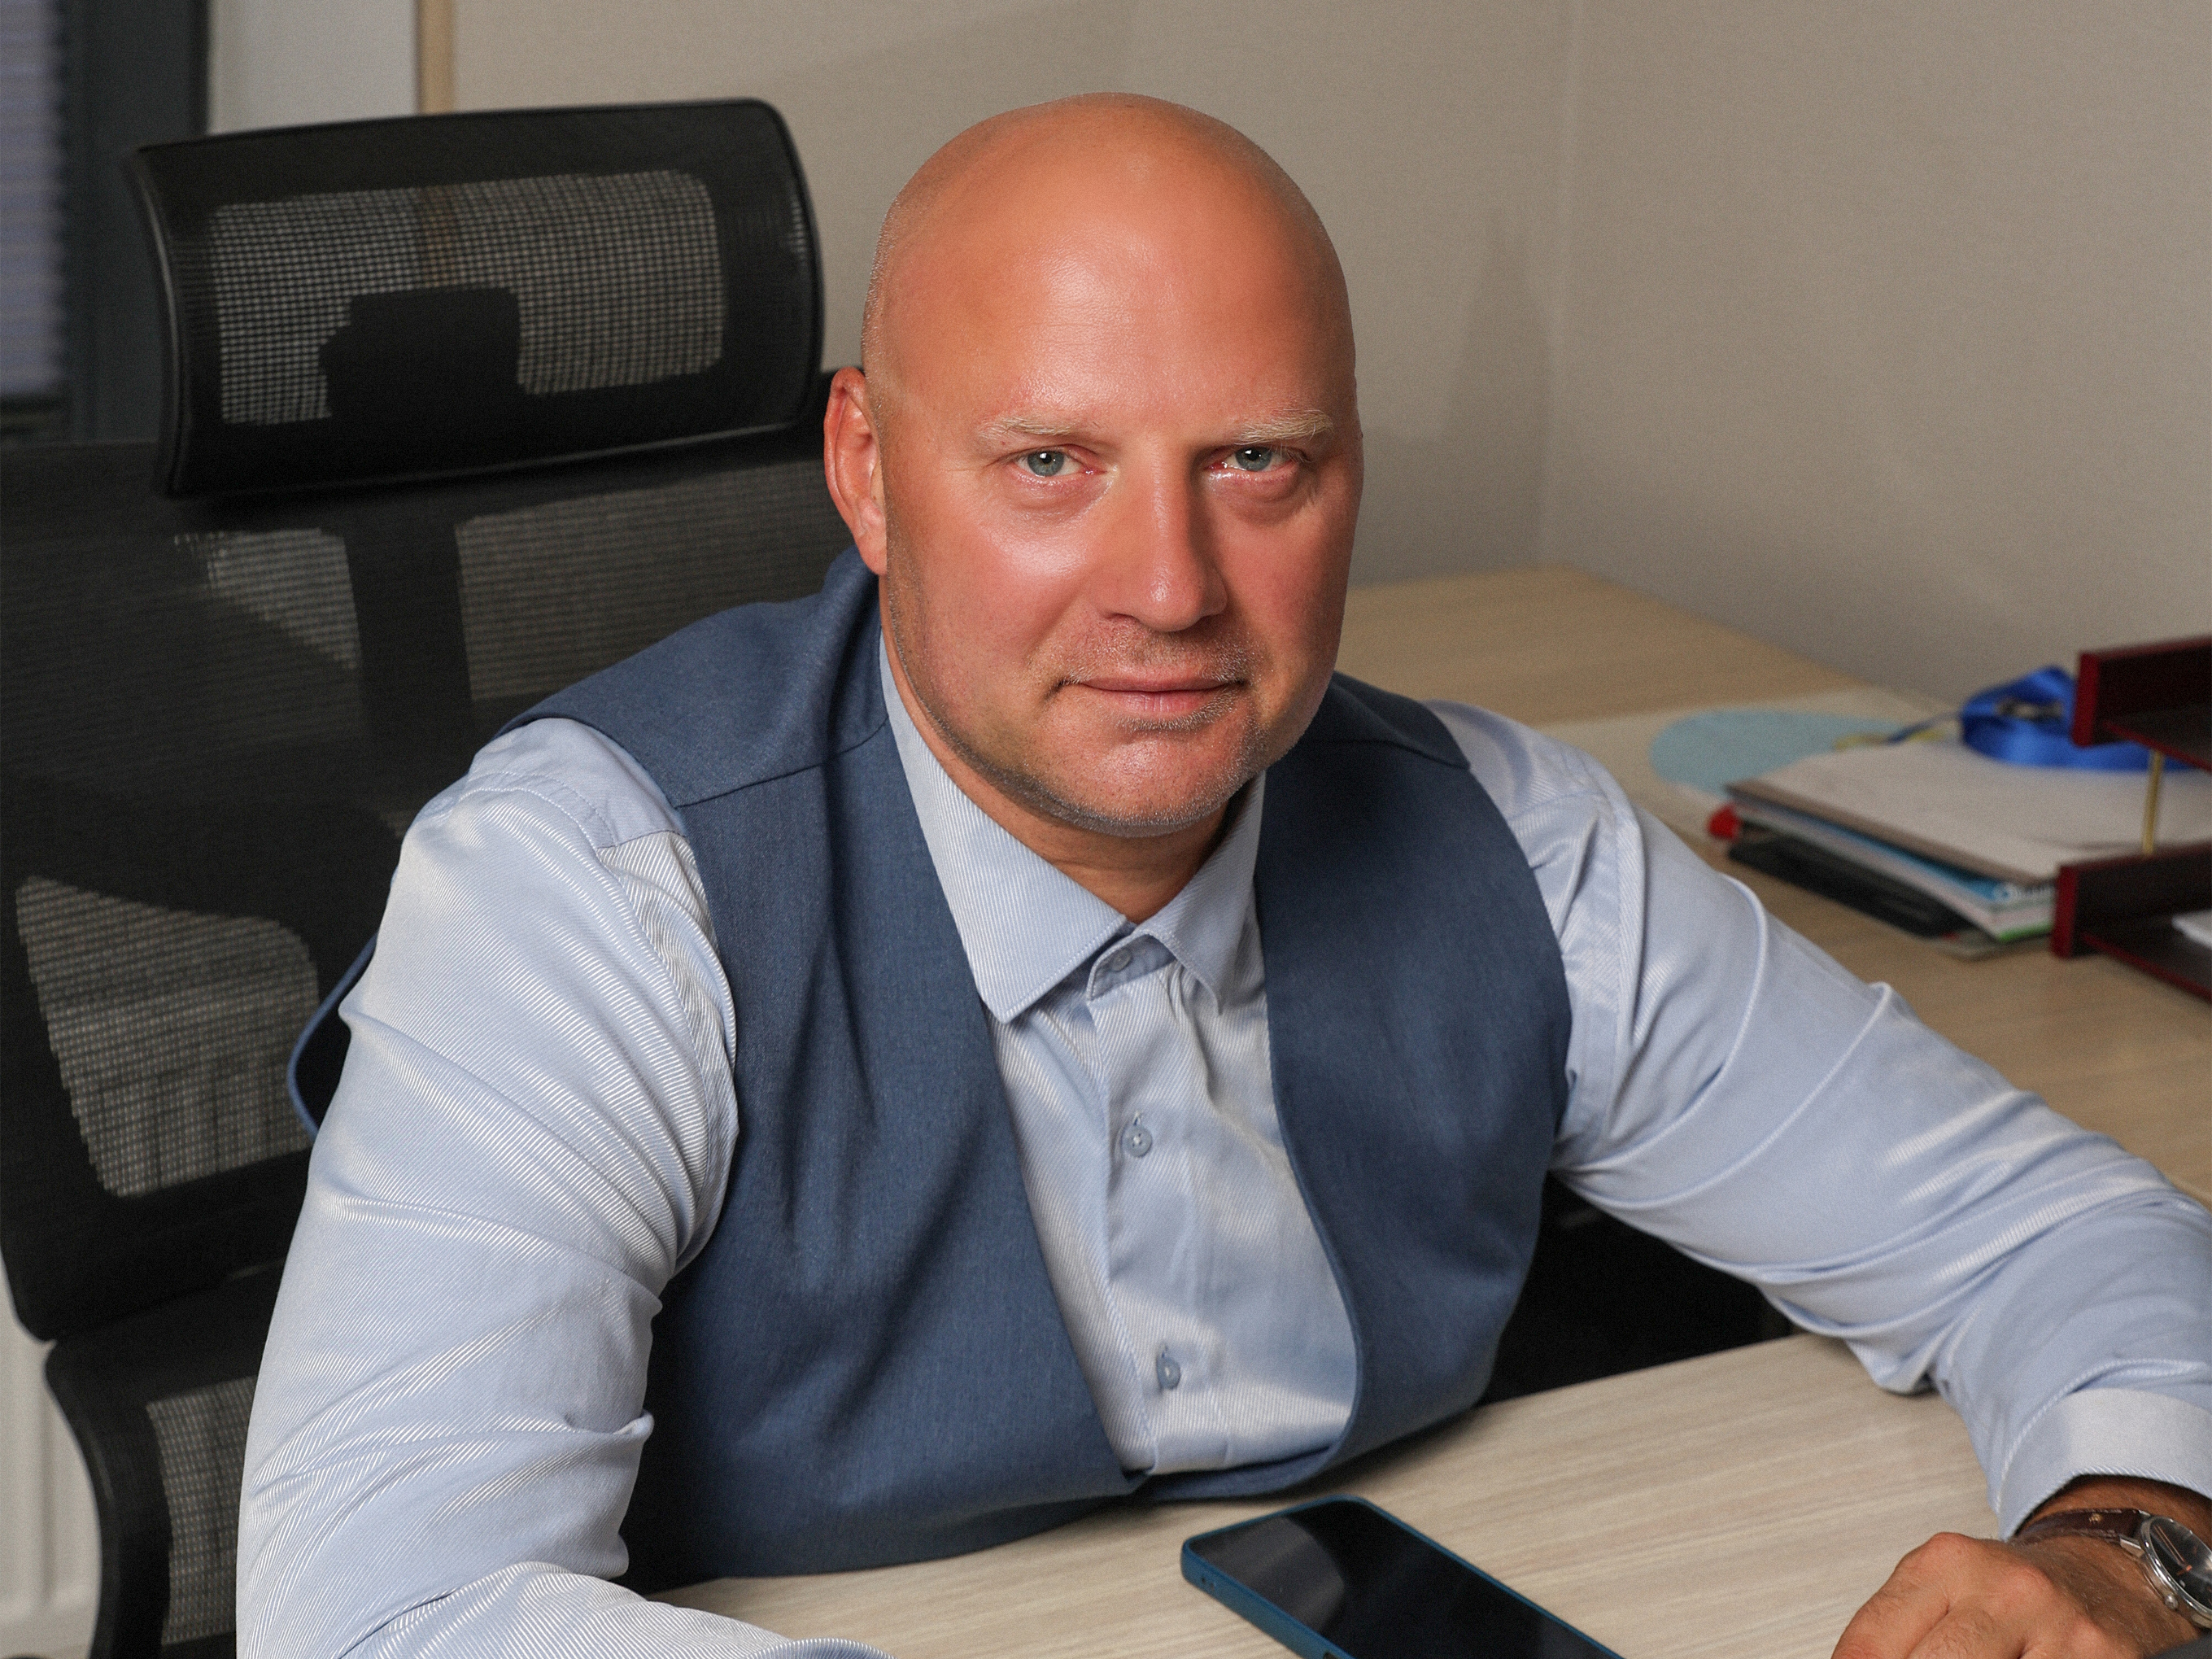
Uzbekistan’s insurance market is undergoing significant change. In 2025, insurance premiums reached UZS 13.46 trillion, up almost 38%, while claims payments approached UZS 3 trillion. Insurance companies are also building capital, regulation is evolving, digital services are developing, and compulsory insurance is being improved. We spoke with Yanis Lasis, CEO of Imkon Sug’urta, about the changes already under way and what should come next for the industry.
— How do you assess the state of Uzbekistan’s insurance market today?
— The market is at a very interesting stage. We are seeing strong momentum: premiums, claims payments and insurers’ capital are growing. That is a sound foundation for the industry’s further development.
But I would not judge the development of insurance solely by the growth rate of premiums. What matters more is whether insurance is becoming a natural part of life for people and businesses. Does someone buy a policy because they understand its value and want protection against the financial consequences of a particular risk? Or because the law, a bank or the terms of a transaction require it?
In my view, the move from ‘insurance because I have to’ to ‘insurance because I understand what it protects me from’ is one of the main signs of a mature market. Growth in numbers matters greatly, but the next stage must be growth in quality.
— The government is actively reforming the industry. How do you view these changes?
— Overall, we support the direction chosen by the regulator. Strengthening insurers’ capital, digitalization, developing reinsurance and improving compulsory insurance are all necessary steps toward a modern market.
Compulsory motor third-party liability insurance is a good example. From 2026, the insured amount rose from UZS 40 million to UZS 80 million. This is an important improvement in the actual protection available to people injured in road accidents. Electronic data exchange is expanding, and a unified insurance billing system is being introduced. All of this makes the market more transparent and technologically advanced.
There is, however, an important practical point: the market needs enough time to implement changes. A new requirement is more than an amendment to a regulation. It means updating IT systems, redesigning business processes, integrating with partners, training employees and testing the customer journey.
That is why continued dialogue between the regulator and market participants is particularly important, both when a change is being discussed and during its technical implementation. The earlier companies understand future requirements and how they will apply, the better they can prepare—and the less inconvenience the changes will cause customers.
— You have worked in European markets for many years. What do you see as one fundamental difference?
— A mature insurance market requires both good regulation and sufficient room for competition. This is especially apparent in compulsory insurance.
If product terms, coverage limits and prices are all strictly fixed, insurers have limited scope to distinguish themselves. Customers then have very few grounds on which to compare companies.
Competition benefits customers above all. When insurers have room to compete on their products, they work harder to win customers through service quality, ease of purchase, speed of claims settlement, additional coverage and other services.
I believe that, as the market develops, we should gradually create more room for this kind of competition. Of course, the necessary level of customer protection and clear rules for everyone must be maintained.
— What is holding back the development of insurance most today?
— One of the main issues is insurance culture. It cannot be changed by a single law, a new compulsory requirement or one advertising campaign.
People need an explanation of why insurance exists, more than an instruction to buy a policy. What is the customer paying for? Which risks are they transferring to the insurer? What happens when an insured event occurs? How can insurance help a family maintain its standard of living, or help a business remain financially stable after a serious incident?
When people understand this, their attitude toward the product changes. A policy stops looking like a formality or an extra expense and becomes a way to manage their own risks.
Responsibility for developing insurance culture does not rest with the regulator alone. Insurers, industry associations, the government, the media and educational institutions all need to work together. We all have an interest in helping customers understand the value of insurance and choose the protection they need with confidence.
— What role should insurance companies play in the economy? Should the aim be to insure as many risks as possible?
— Insurance companies serve an important economic function. We pay taxes, create jobs and, most importantly, help people and businesses cope with the financial consequences of difficult situations.
When a serious insured event occurs, an insurer takes on part of a financial burden that could otherwise be critical for an individual or a company. That is one of insurance’s key economic functions: risk does not disappear, but its consequences become more predictable and manageable.
At the same time, I do not believe that developing the insurance market means insuring absolutely everything. Insurance always involves a balance between transferring risk to an insurer and retaining responsibility as a customer.
Some risks genuinely make sense to transfer to an insurer, especially when the potential loss could be too great for a person or business to bear. But the customer, the company or, for example, the bank must also remain responsible for assessing risks, making decisions and managing those risks.
Insurance should not become a way to relinquish all responsibility. If every risk is automatically passed to the insurer, others may have less incentive to manage it well.
I think this is the approach that characterizes a mature market: understanding which risks it makes sense to transfer to an insurer, which to retain, and how to allocate responsibility properly among everyone involved, instead of trying to insure everything.
Ultimately, insurance is not meant to eliminate risk itself. That is impossible. Our task is to make its financial consequences manageable and help people or businesses remain resilient when the unexpected happens.
— What would you like Uzbekistan’s insurance market to look like in a few years?
— More mature and more focused on people.
The market is already growing quickly in quantitative terms. The next stage is qualitative: well-capitalized companies, modern and clear regulation, digital products, genuine competition and, most importantly, customers who understand the value of insurance and make informed decisions about protecting themselves against risks.
Another important element is the proper allocation of responsibility. An insurer should be a reliable partner that takes on risks customers would genuinely struggle to bear alone. But customers themselves—whether individuals, businesses or financial institutions—must also take responsibility for their decisions and for managing risk.
I believe a mature insurance market emerges from this combination: strong insurers, sensible regulation, competition, technology and informed customers.
Ultimately, insurance does not exist for the sake of a policy or simply to sign a contract. It exists so that people and businesses do not have to face a difficult situation alone. If the industry develops around this idea, the prospects for Uzbekistan’s insurance market are very good.

Links to the company's corporate website must be provided when other persons use the information materials on the corporate website
Links to the company's corporate website must be provided when other persons use the information materials on the corporate website